50/30/20 budget calculator
Enter your monthly take-home pay. The 50/30/20 guide splits it into needs (50%), wants (30%) and savings (20%) — plan your categories and see exactly where you're over or under.
- ✓ Free, no sign-up, no bank login
- ✓ 50/30/20 or zero-based
- ✓ Monthly or weekly
- ✓ Print, PDF or Excel/Sheets
My monthly budget
Take-home pay: $5,000 / month
Left after your plan
$150 / month
- $150 a month isn't planned yet — moving it to savings would raise your savings rate to 22%.
- Needs take 60% of your pay (the 50/30/20 guide is 50%). Housing is usually the biggest lever.
- You're saving 19% — $50 a month short of 20%. Even 1% more each month adds up.
Saved automatically in this browser only. Not sure of your take-home pay? Use the salary after taxes calculator.
The 50/30/20 rule in one minute
- 50% needs — housing, utilities, groceries, transportation, insurance, minimum debt payments.
- 30% wants — dining out, shopping, subscriptions, travel, hobbies.
- 20% savings & debt — emergency fund, retirement, extra payments on debt.
It's a guide, not a law. If needs run high, protect your savings first and trim wants. Prefer to assign every dollar? Use the monthly budget planner in zero-based mode.
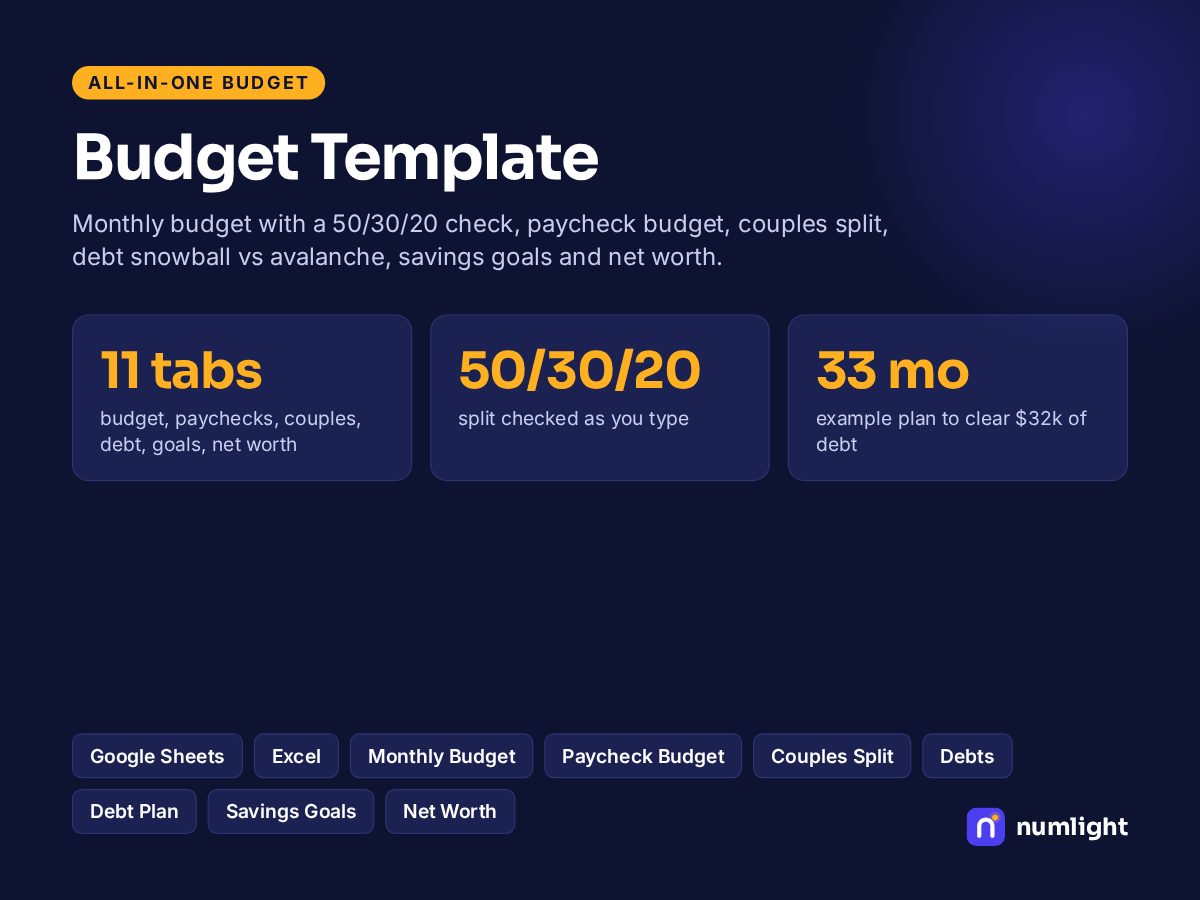
Get the free Monthly Budget Kit (PDF)
The 50/30/20 split at your income, a printable monthly worksheet and the 5-minute subscription audit — free when you join our weekly money email.
Free, about one email a week. Unsubscribe anytime — we never sell your email. Privacy
Frequently asked questions
How does the 50/30/20 rule work?+
Split your monthly take-home pay: 50% for needs, 30% for wants and 20% for savings and extra debt payments. On $5,000 a month that's $2,500 for needs, $1,500 for wants and $1,000 for savings.
What counts as a need vs a want?+
Needs are what you must pay to live and work: housing, utilities, groceries, transportation, insurance, childcare and minimum debt payments. Wants are everything optional — dining out, shopping, streaming, travel, upgrades.
What if my needs are more than 50%?+
That's common with high rent or a big car payment. Keep savings as close to 20% as you can, trim wants, and look at your largest need — housing is usually the biggest lever over time.
Is the 50/30/20 rule based on gross or net income?+
On take-home (net) pay — after taxes and payroll deductions. 401(k) contributions taken from your paycheck can count toward the 20% savings.